Key Takeaways
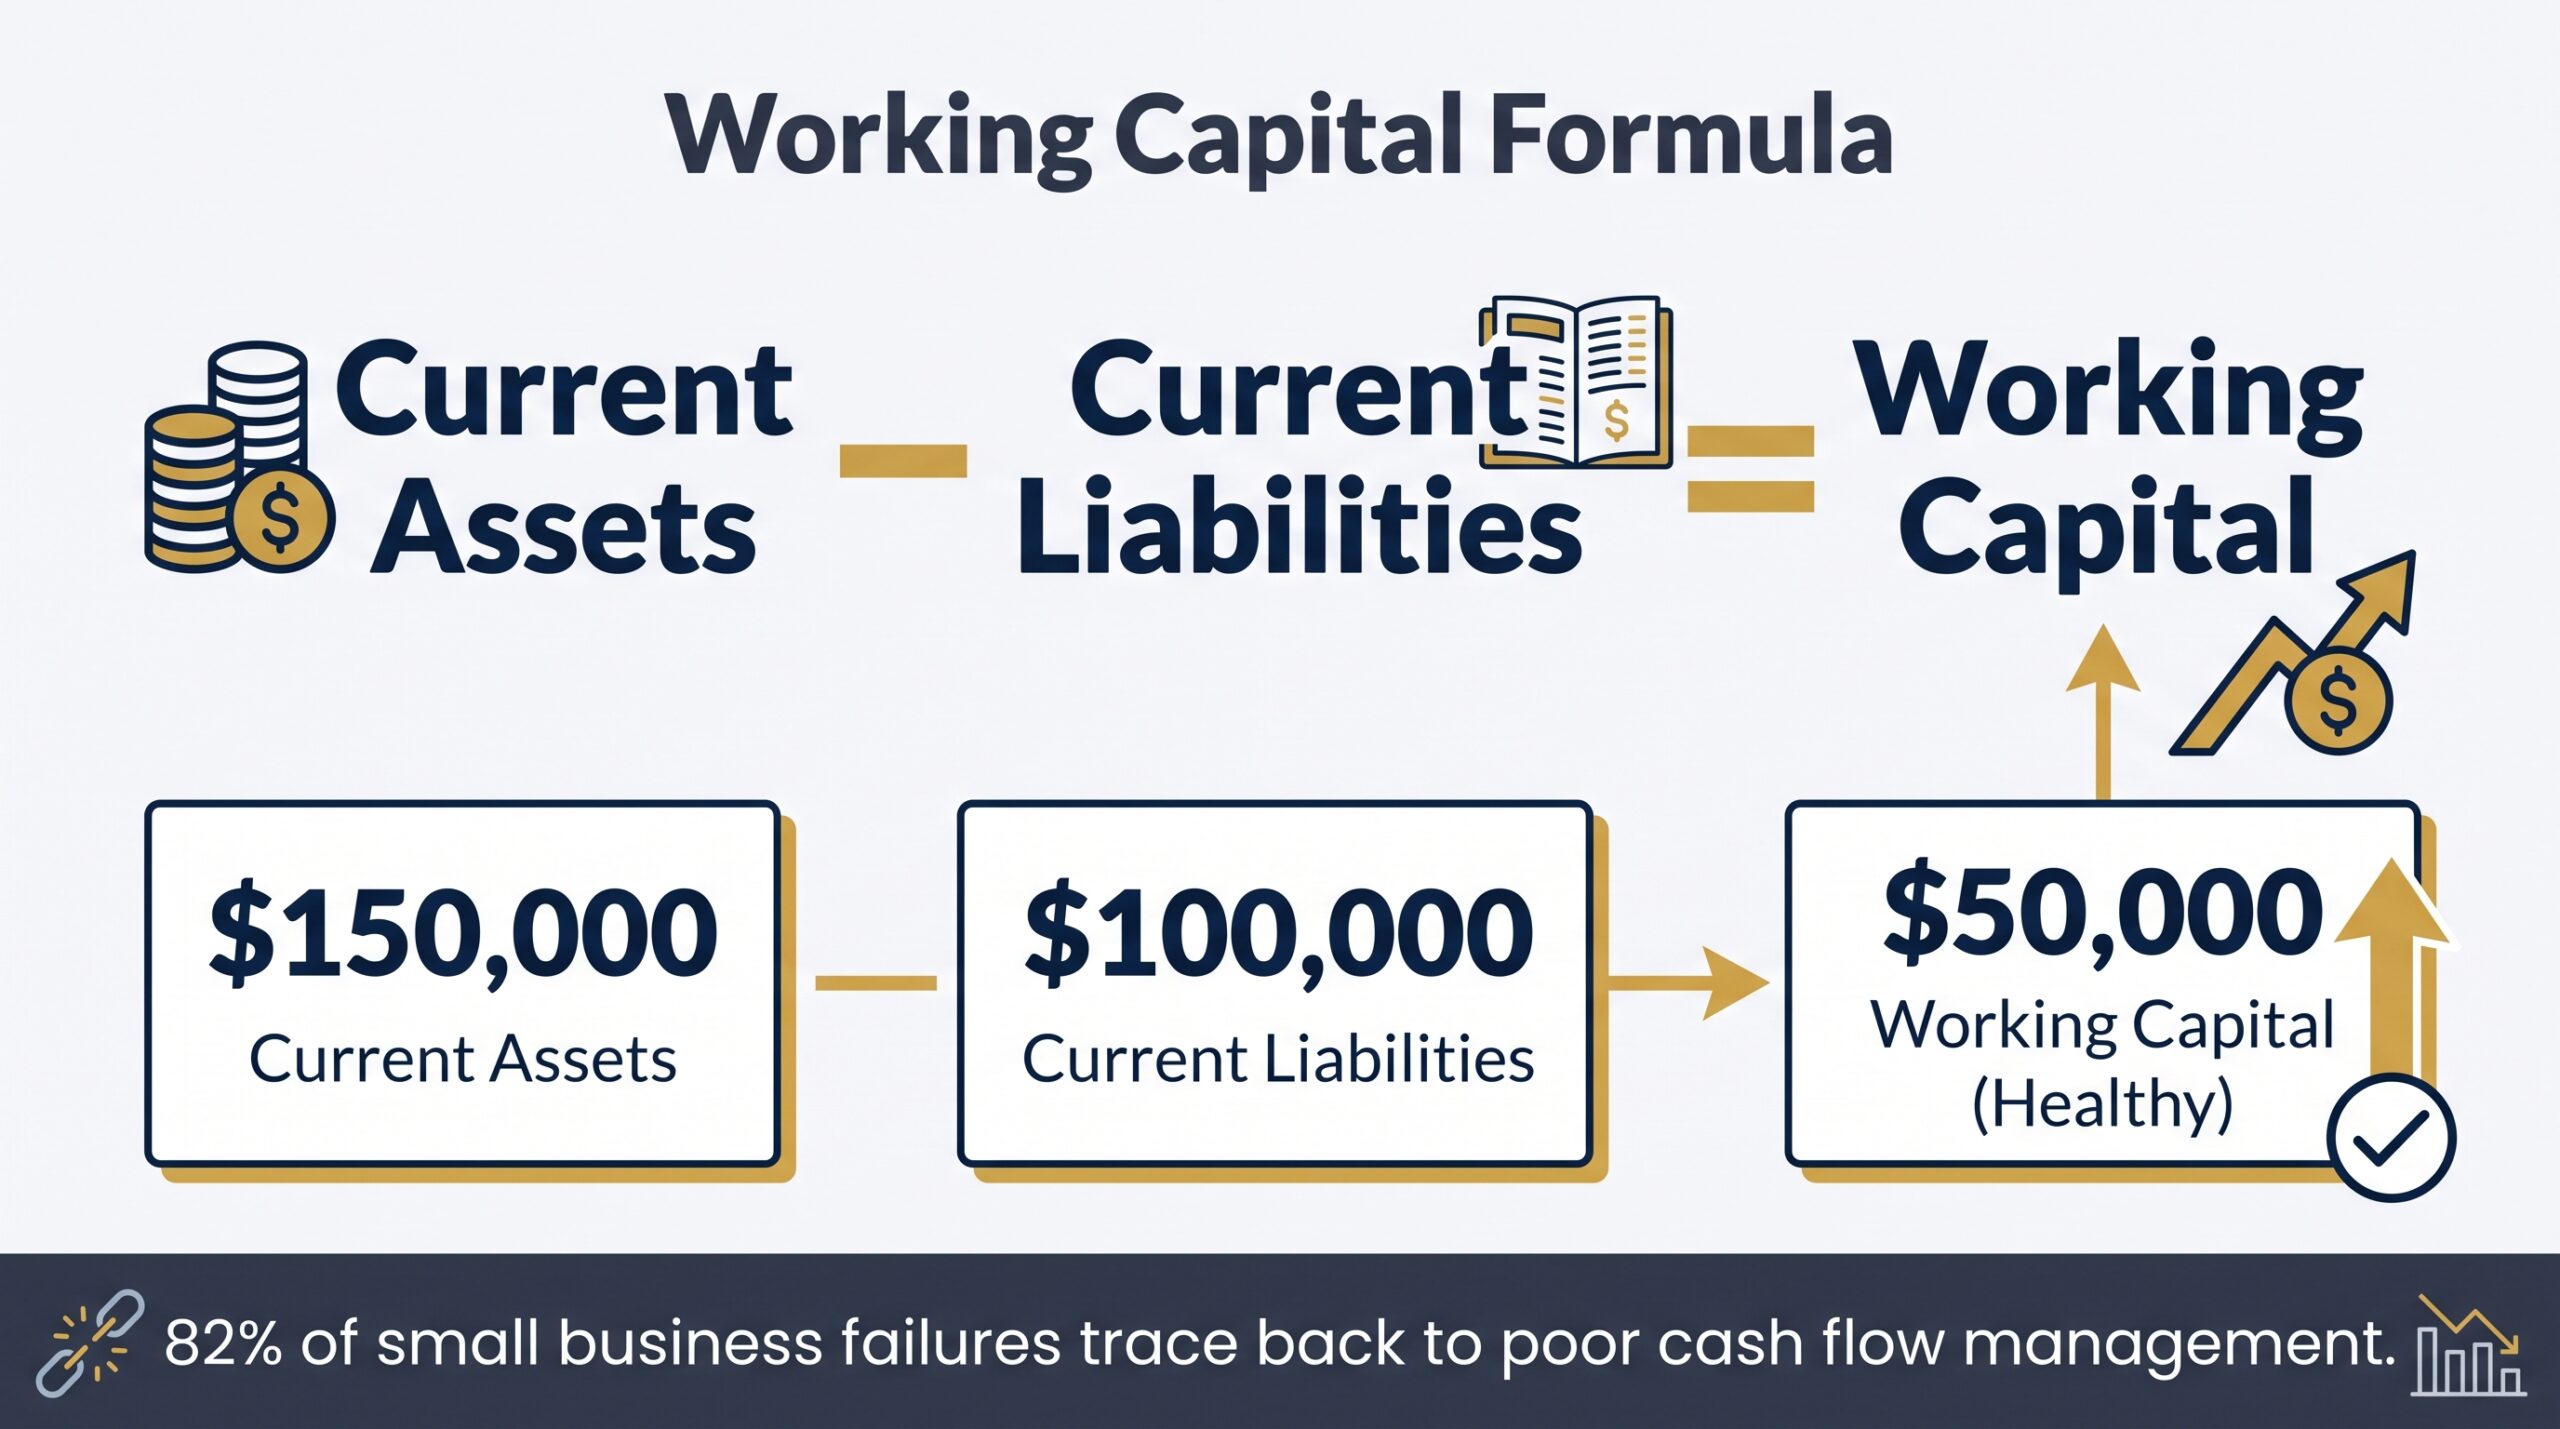
82% of small business failures trace back to poor cash flow management; working capital loans exist specifically to close the gap between money going out and money coming in.
The SBA's Working Capital Pilot (WCP) program offers a revolving line of credit up to $5 million with a maximum maturity of 60 months for businesses with at least one year of operating history, according to sba.gov; the lender sets its own credit standards.
A 1.30 factor rate on a six-month merchant cash advance repaid daily works out to an APR of roughly 110% (an example; the exact figure depends on the term and payment schedule); always convert factor rates to APR before comparing any loan offers side by side.
Bad credit doesn't automatically disqualify you: credit requirements vary by lender and product, and some providers weigh your revenue and cash flow more heavily than your score.
Online lenders fund working capital loans in 24–72 hours; SBA loans usually take several weeks; your urgency should determine which lender type you target first.
A revolving line of credit only charges interest on what you draw. A $100,000 line where you use $20,000 costs interest on $20,000, making it the smarter structure for seasonal or unpredictable cash gaps.
Working capital loans make sense when the cost of borrowing is less than the cost of inaction. If cash flow deficits are chronic rather than seasonal, more debt accelerates the problem instead of solving it.
Cash flow gaps don't care about your revenue. They'll stall a thriving business just as fast as a struggling one. A working capital loan for small business owners gives you fast access to funds that keep daily operations running when timing works against you.
This guide covers every loan type, what you'll actually qualify for, and how to apply. Let's get into it.
What Is a Working Capital Loan for Small Business?
A working capital loan for small business is short-term financing designed to cover everyday operational costs, payroll, rent, inventory, utilities, not long-term assets. It's not an equipment loan, an SBA 504, or a commercial real estate mortgage. Those fund things you own for years.
A working capital loan funds the gap between money going out and money coming in. That's it.
According to SCORE, the SBA's mentoring partner, 82% of small businesses fail due to cash flow problems. That single stat explains why lenders built an entire loan category around this problem.
How Working Capital Loans Differ from Other Business Loans
Equipment loans are secured by the equipment itself and typically run 3 to 7 years. SBA 504 loans fund commercial property and machinery with repayment terms up to 25 years.
A small business working capital loan works differently: shorter working capital loan terms (3 to 18 months is common), faster funding, and no requirement to tie proceeds to a specific asset purchase. You're borrowing against your business's cash flow capacity, not a physical asset.
That makes approval faster but rates higher. It's a trade-off worth knowing upfront.
The Working Capital Formula: Do You Actually Need a Loan?
Before you apply for any working capital loans for small business, run this calculation first:
Working Capital = Current Assets − Current Liabilities
If your business holds $150,000 in current assets (cash, receivables, inventory) and carries $100,000 in current liabilities (short-term debt, accounts payable), your working capital is $50,000. Positive is healthy. Negative means you may genuinely need a loan, and lenders use this exact number to evaluate your application.
The working capital formula, as defined by Investopedia and the Corporate Finance Institute, is the foundational metric any lender reviews before approving a working capital loan for small business. Know your number before they ask.
Best Working Capital Loan Options for Small Businesses
Not every working capital loan for small business works the same way. Your revenue model, credit score, and how fast you need funds determines which option actually fits. Here are the seven types worth knowing.
SBA 7(a) Loans and the 2024 Working Capital Pilot Program
SBA 7(a) loans can fund working capital, and the SBA's 7(a) Working Capital Pilot (WCP) adds a revolving line of credit of up to $5 million with a maximum maturity of 60 months for businesses with at least one year of operating history, according to sba.gov.
The SBA sets eligibility and a maximum interest rate, while the lender sets its own credit standards and asks for a full financial documentation package. For the programs, requirements and how to apply, see our guide to SBA 7(a), 504 and microloans.
SBA Microloans
SBA Microloans cap at $50,000 with an average loan size of $13,000 and terms up to 7 years. Nonprofit intermediary lenders fund these, which means more flexibility on credit, but slower approvals.
They're best for early-stage businesses that can't access conventional working capital loans for small businesses yet.
Business Lines of Credit
A revolving line of credit lets you draw, repay, and draw again, only paying interest on what you use. APRs typically run 10–35%. It's one of the most flexible working capital small business loan structures available, and most established businesses should have one open before they need it.
Short-Term Business Loans
Fast funding, sometimes same-day, with terms from 3 to 18 months. The speed costs you. APRs range from 15% to 99%, so run the math before you sign.
These work for urgent gaps. They're not a long-term cash flow strategy.
Invoice Financing
If your business invoices other businesses, you can borrow against unpaid receivables. Lenders advance 80–90% of the invoice value and charge 1–5% of the invoice as a fee. No collateral required. No waiting 60 days for a client to pay.
Merchant Cash Advances
An MCA gives you a lump sum in exchange for a percentage of future sales. Factor rates run 1.10 to 1.50, meaning you repay $1.10 to $1.50 for every dollar advanced.
That's expensive. Treat MCAs as a last resort, not a working capital loan for business strategy.
Working Capital Loans for Bad Credit
Bad credit doesn't automatically disqualify you. Credit requirements vary by lender and product: merchant cash advances and invoice financing lean more on your sales or receivables than on your score, and nonprofit microlenders often look beyond the score too.
Explore your full lender options before assuming you're stuck.
Working Capital Loan Options Compared
Use this table to match your situation to the right working capital loan for small business before you spend time applying. Pricing, terms and requirements vary by lender; your actual offer depends on credit, revenue, and time in business.
Option | How It Works | Priced With | Best For |
|---|---|---|---|
Bank term loan | A lump sum repaid on a fixed schedule | Interest rate (APR) | Established businesses with strong financials |
SBA 7(a) and Working Capital Pilot | A term loan or revolving line partly guaranteed by the SBA; WCP lines go up to $5 million with a maximum maturity of 60 months, per sba.gov | Interest rate, with a maximum set by the SBA | Businesses that can wait several weeks and provide full financials |
SBA Microloan | Up to $50,000 through nonprofit intermediary lenders, with terms up to 7 years, per sba.gov | Interest rate, generally 8% to 13% per sba.gov | Early-stage businesses |
Business line of credit | Draw, repay and draw again up to a limit | Interest rate (APR), charged on what you draw | Seasonal or unpredictable cash gaps |
Short-term online loan | A lump sum repaid daily or weekly over months | Interest rate or a fixed fee; compare offers by APR | Fast needs and shorter credit histories |
Invoice financing | An advance against unpaid customer invoices | A fee per invoice | B2B businesses waiting on customers to pay |
Merchant cash advance | An advance repaid from a share of future sales | Factor rate (a fixed total cost) | Card-heavy businesses that need speed |
Here's something most working capital loan lenders won't tell you upfront: APR and factor rates aren't the same calculation. For example, a 1.30 factor rate on a six-month MCA repaid in daily payments works out to an APR of roughly 110%; the exact figure depends on the term and payment schedule, which our merchant cash advance calculator lets you enter.
Always convert to APR before comparing any small business working capital loan offers side by side. Always.
How to Qualify for a Working Capital Loan
Most lenders evaluate the same five factors when you apply for a working capital loan for small business. Requirements vary by lender and product, but these are the factors most of them look at:
A personal credit score that meets the lender's minimum, which varies by lender and product
6 months to 2+ years in business
$30,000–$150,000+ in annual revenue
No open bankruptcies (traditional lenders want a 7-year clean record)
Completed application with bank statements and business tax returns
Credit Score Requirements
Online lenders and merchant cash advance providers generally accept lower credit scores than banks. Banks and SBA lenders typically look for stronger credit, and each lender sets its own minimum.
Your score determines your rate as much as your approval. A stronger score can mean a noticeably lower APR on the same loan amount, and that's real money over the life of the loan.
Time in Business Requirements
Online lenders often fund businesses as young as 3–6 months. Banks often want about two years of operating history; the SBA's Working Capital Pilot asks for at least one year.
Less than a year in business? Focus on online lenders, invoice financing, or nonprofit microloans first. Don't waste time on applications you won't win.
Revenue Requirements
Revenue minimums vary by lender and product. Online lenders often accept lower annual revenue than traditional banks, which typically want more.
SBA 7(a) has no hard revenue floor, but your debt service coverage ratio has to work. Lenders want to see you generating enough to repay comfortably. Thin margins make that harder to demonstrate, regardless of your top-line revenue.
Other Factors Lenders Evaluate
Lenders also check your working capital ratio to assess financial health. A ratio below 1.0 signals you're already underwater. They'll review industry risk, existing debt load, and whether you have collateral available.
Some online lenders skip collateral entirely for loans under $50,000. Banks rarely do.
Lender Type | Min. Credit Score | Min. Time in Business | Min. Annual Revenue |
|---|---|---|---|
Online Lenders | Varies by lender | 3–6 months | $30,000+ |
Traditional Banks | Varies by lender | 24 months | $100,000+ |
SBA Loans | Set by the lender | Varies by program (WCP: 1 year) | Varies (DSCR-based) |
Invoice Financing | Varies by lender | 3–6 months | $50,000+ in receivables |
MCA Providers | Varies by lender | 3–6 months | $50,000+ |
How to Apply for a Working Capital Loan: Step by Step
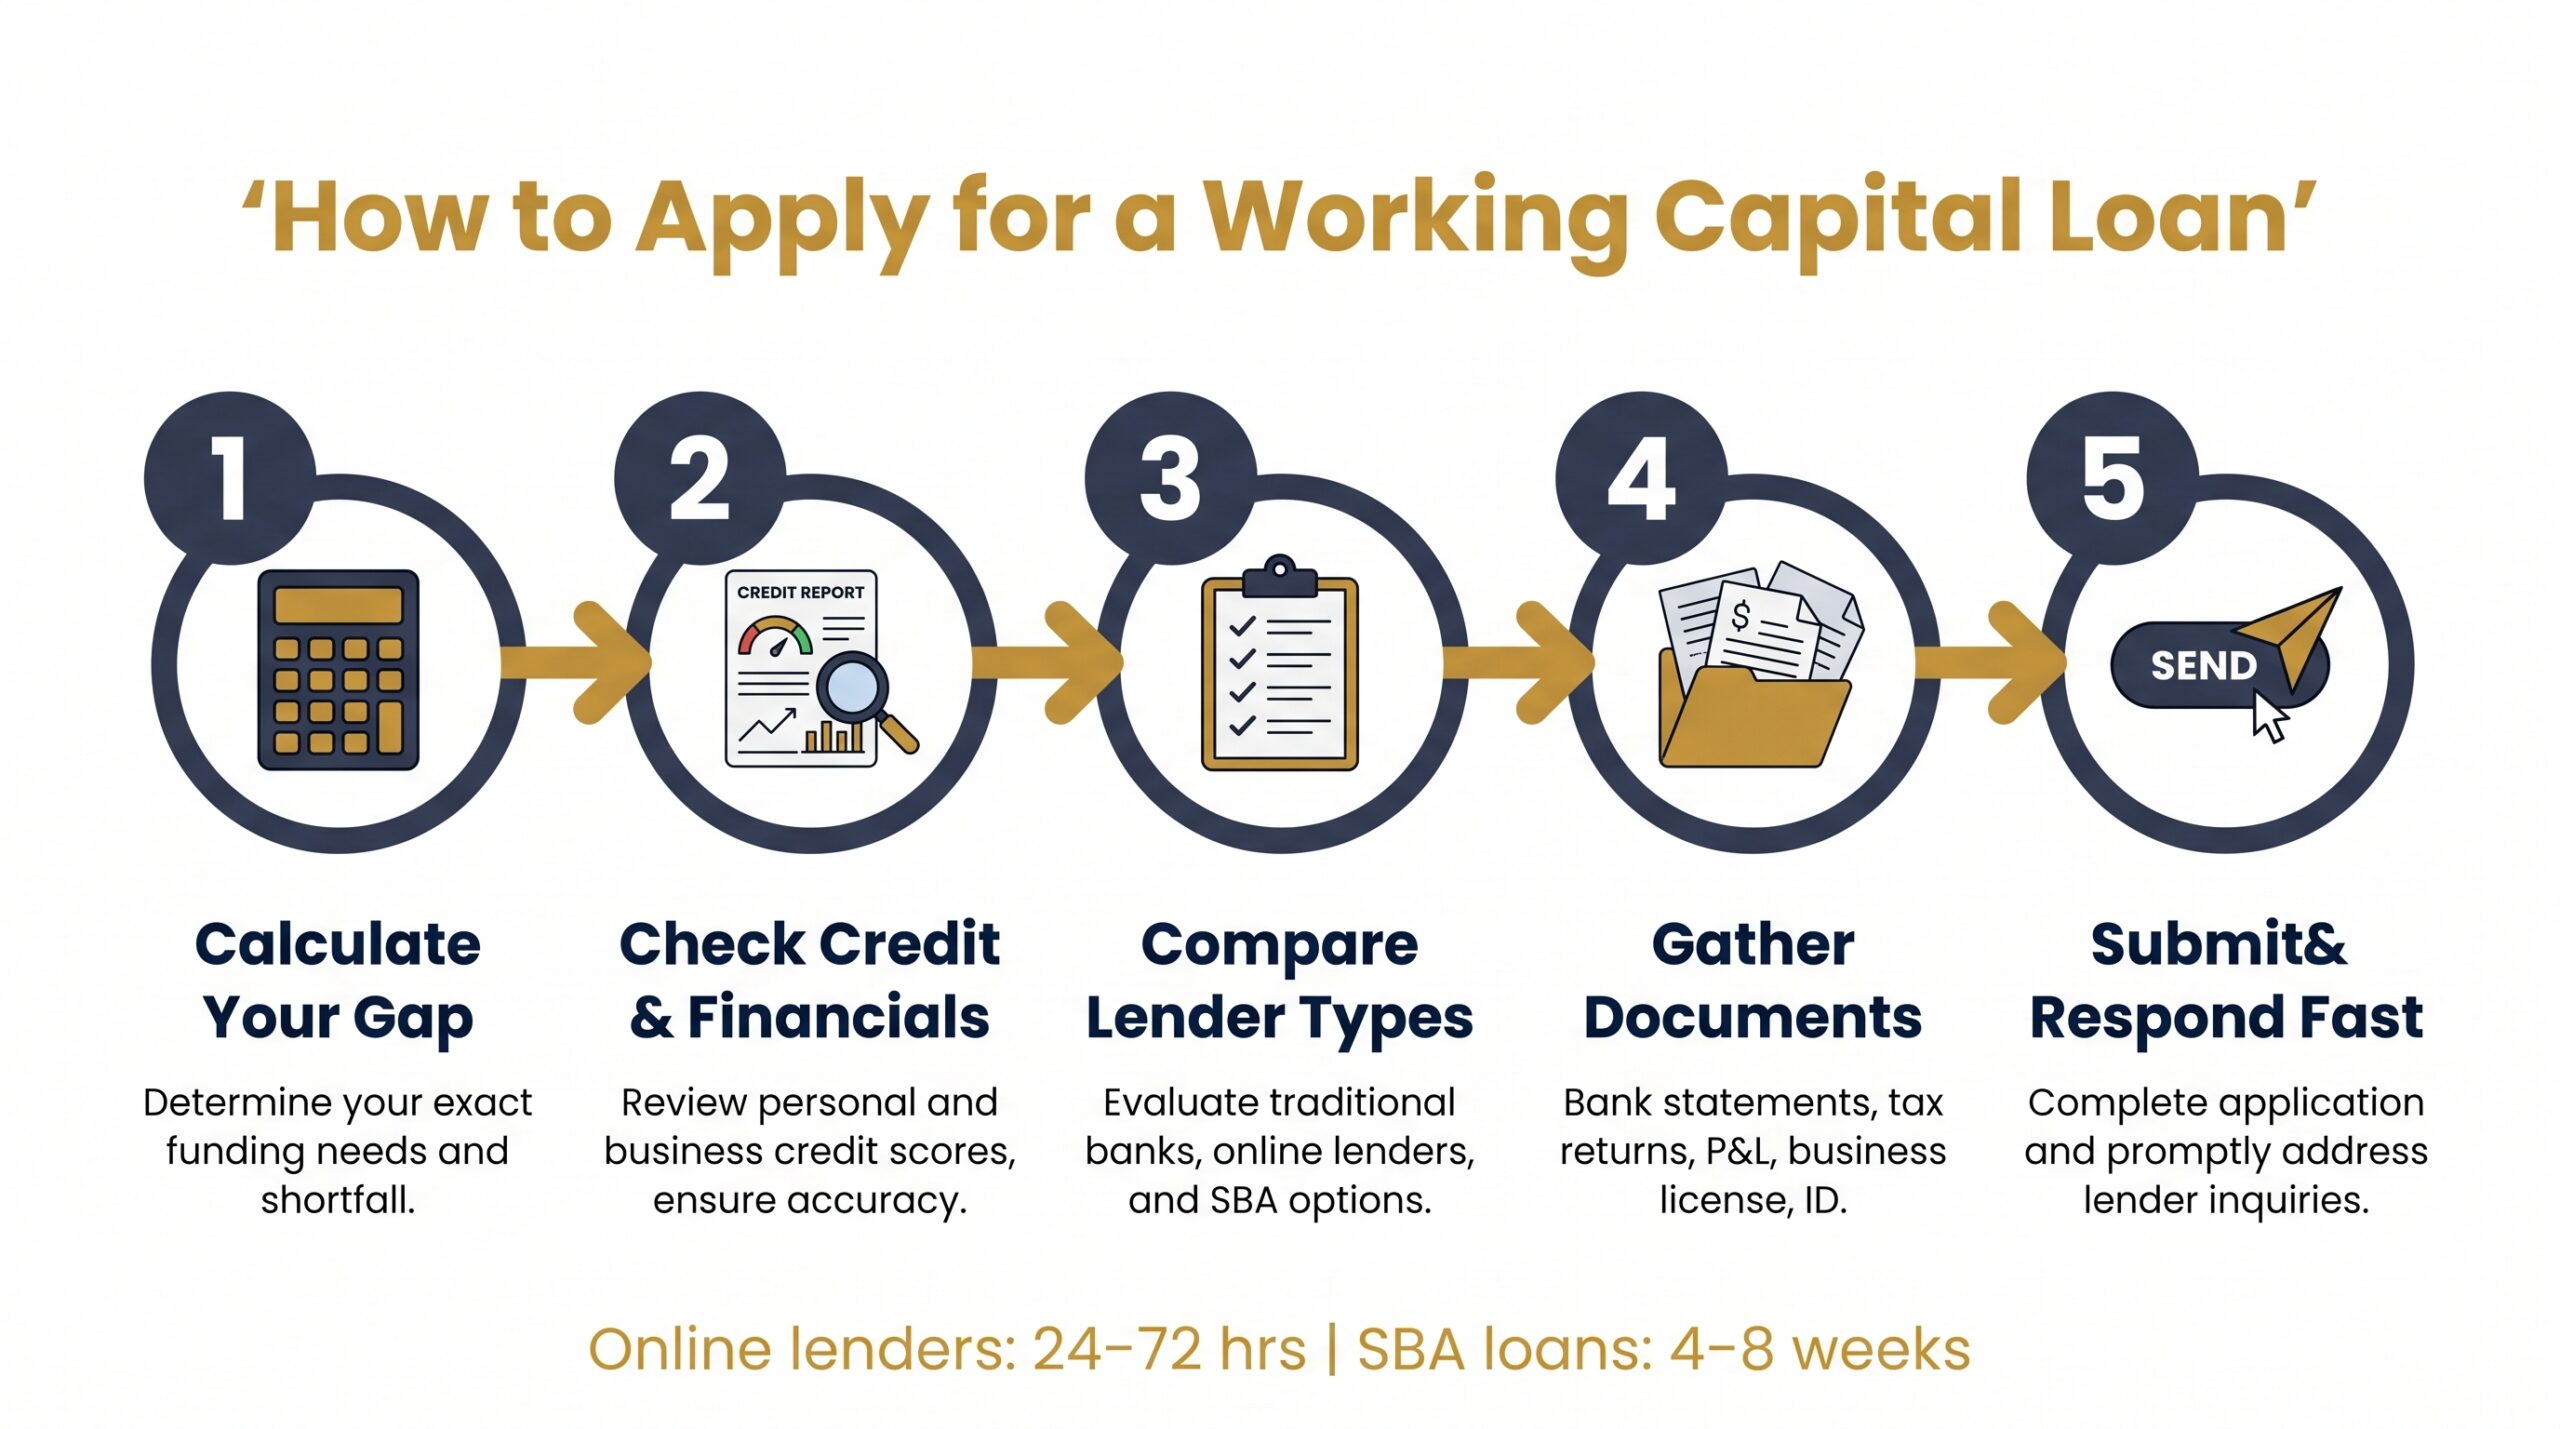
With online lenders, the application process moves fast, sometimes same-day approval and funding within 24–72 hours. SBA loans usually take several weeks. Either way, the prep work is the same, and doing it right the first time matters.
Calculate exactly how much you need. Use the working capital formula to quantify your gap. Borrowing too little leaves you short. Borrowing too much means unnecessary interest costs.
Check your credit score and business financials. Pull your personal credit report at annualcreditreport.com. Calculate your current ratio and monthly revenue average. Know your numbers before a lender does.
Compare lender types. Use the comparison table in this guide to match your credit score, time in business, and revenue to the right working capital loan small business options.
Gather your documents. Most lenders require:
3–6 months of business bank statements
Business tax returns (1–2 years)
Profit and loss statement
Business license
Government-issued ID
Submit and respond fast. Incomplete applications kill deals. If a lender requests additional documents, respond within 24 hours. Delays push your file to the back of the queue, especially with SBA loans.
One practical tip: apply to 2–3 working capital loan lenders simultaneously. Comparing real offers beats comparing estimates every time.
Working Capital Loan Costs: What to Expect
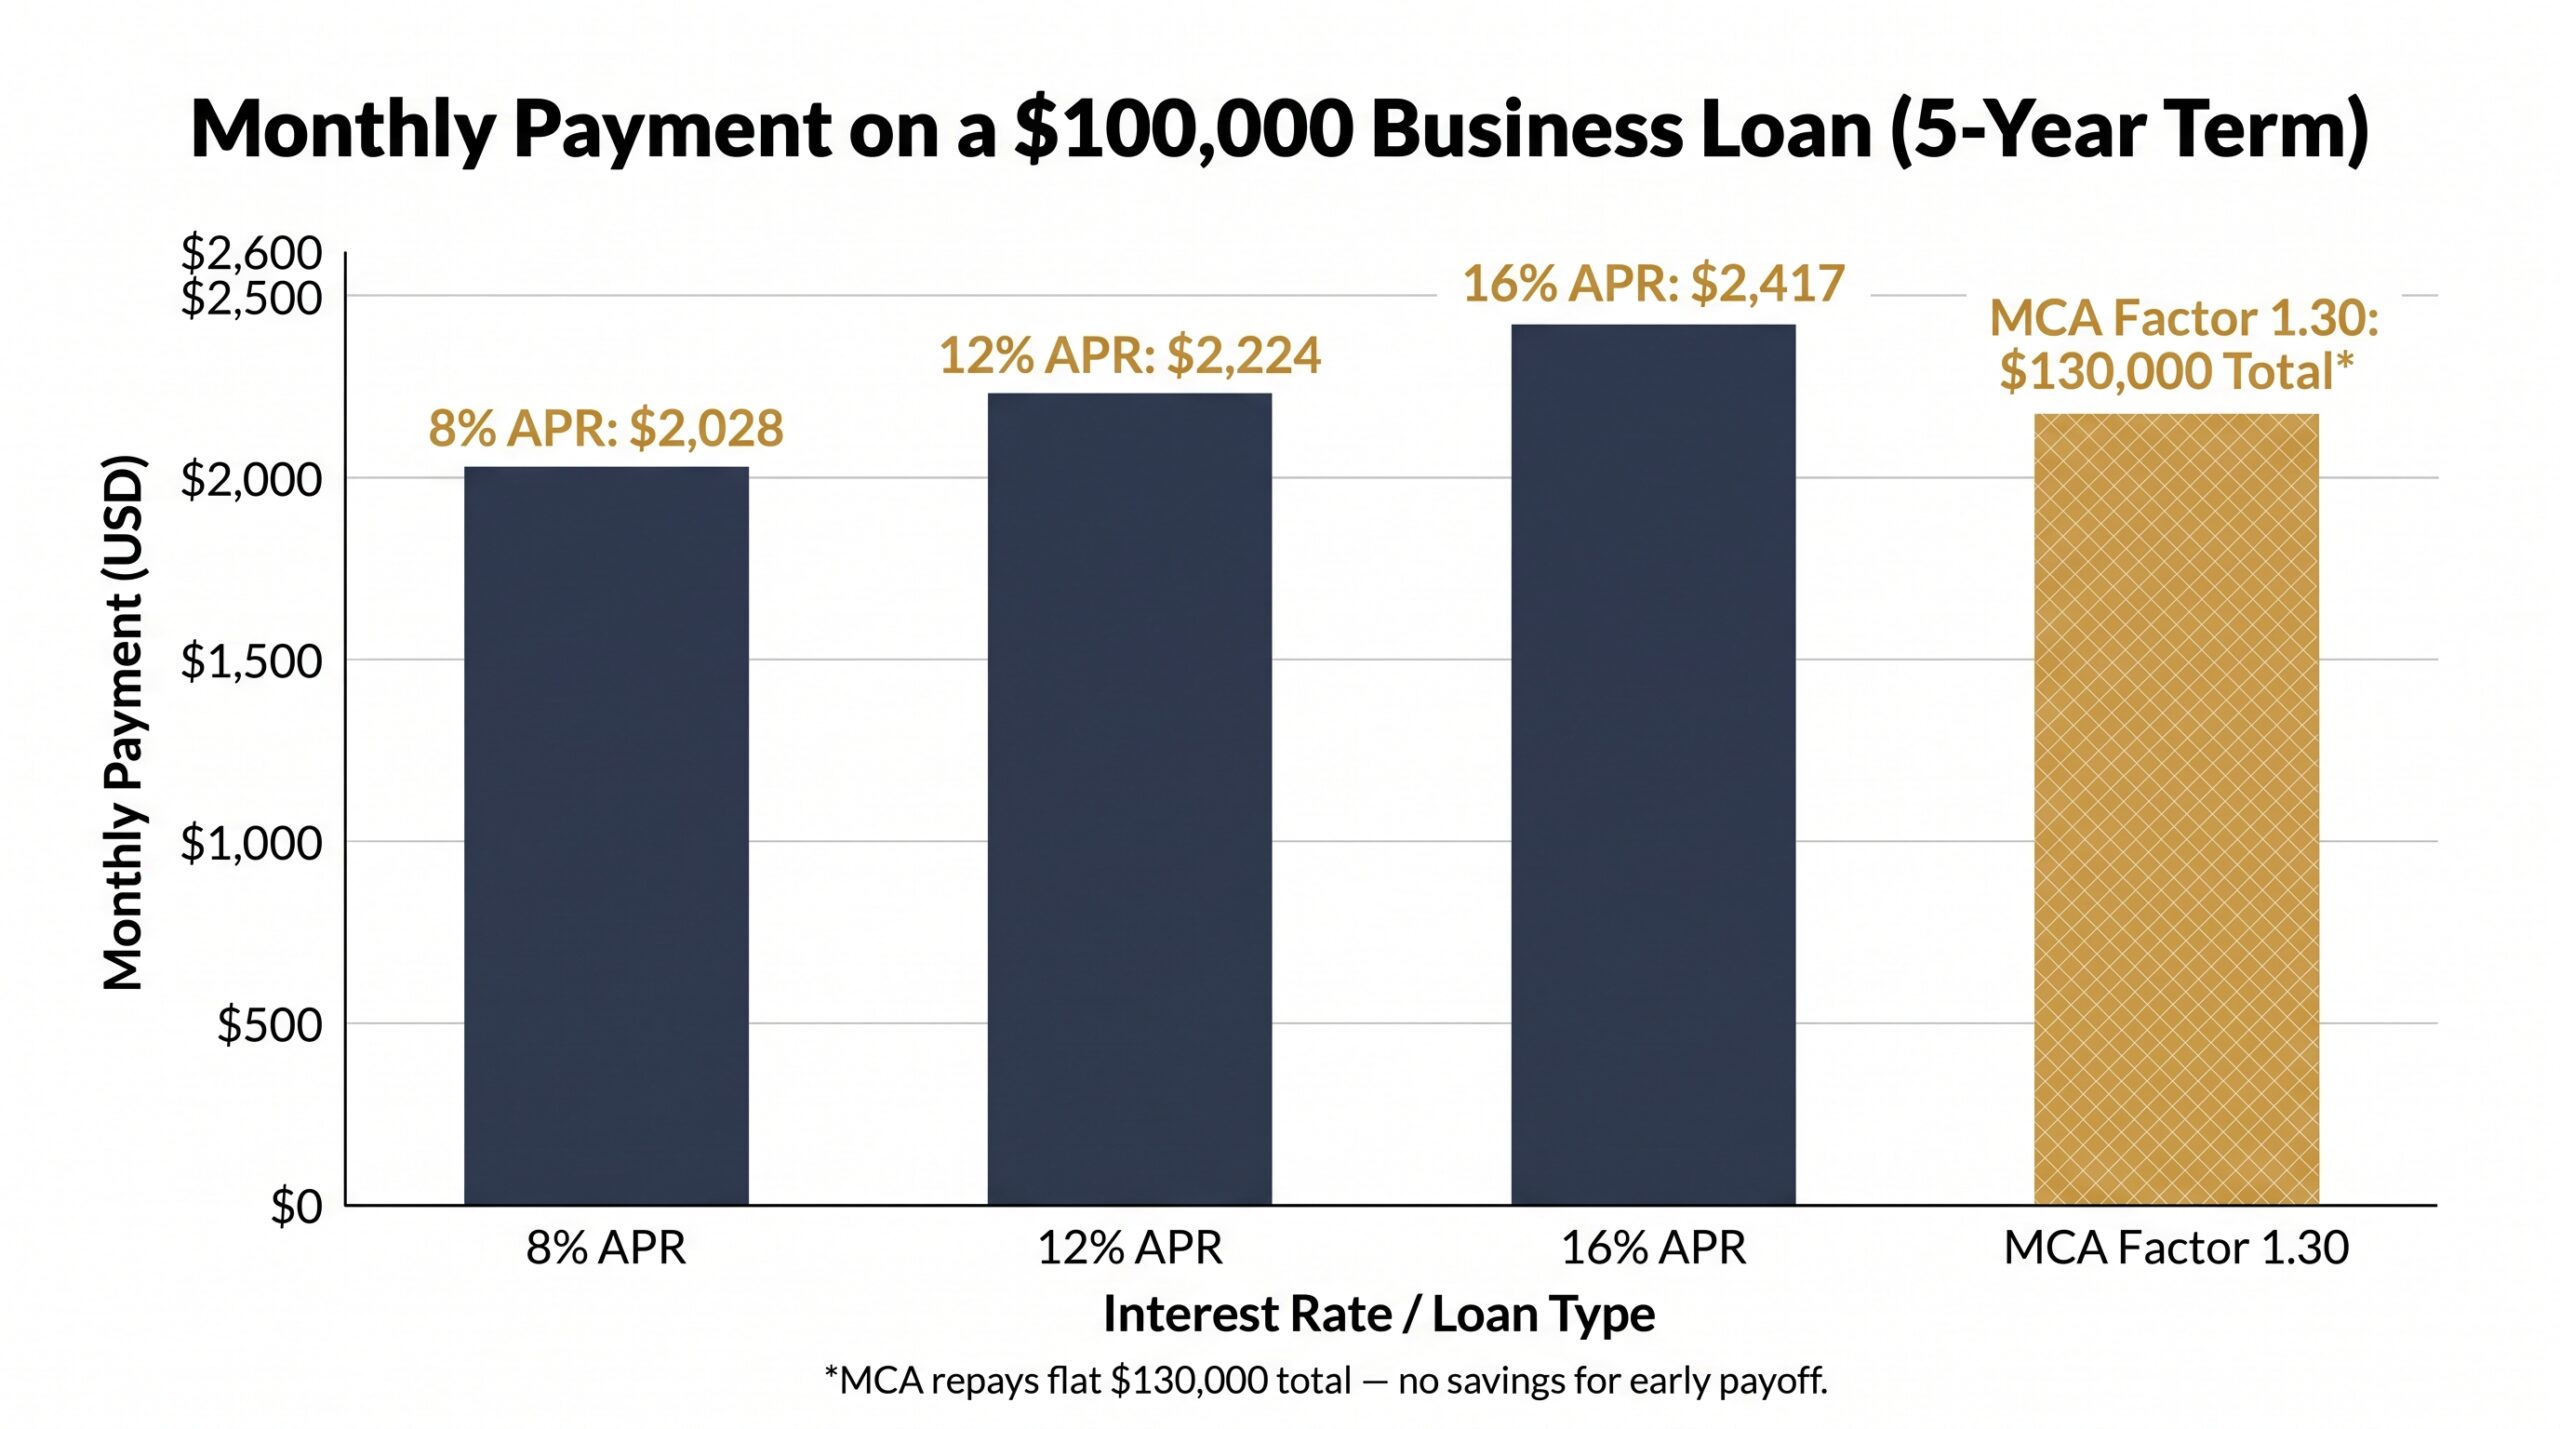
Rate shopping without knowing your payment math is just guesswork. Here's what a working capital loan for small business actually costs at different rate levels, so you can walk into any conversation with a lender already knowing the numbers.
How Much Is the Monthly Payment on a $100K Business Loan?
On a $100,000 loan with a 5-year term, your monthly payment shifts significantly with rate:
Loan Amount | APR | Term | Monthly Payment | Total Repaid |
|---|---|---|---|---|
$100,000 | 8% | 5 years | $2,028 | $121,680 |
$100,000 | 12% | 5 years | $2,224 | $133,440 |
$100,000 | 16% | 5 years | $2,417 | $145,020 |
$100,000 | Factor 1.30 (MCA) | Varies | Daily/weekly draw | $130,000 flat |
That MCA row matters more than it looks. A 1.30 factor rate on a $100,000 advance means you repay $130,000 total. Paying early doesn't necessarily lower that total, so ask the provider whether paying early changes the total cost.
That's a fundamental difference from any traditional small business working capital loan, and it catches a lot of business owners off guard.
How Hard Is It to Get a $1 Million Business Loan?
Harder than most owners expect. Requirements vary by lender and product, but a loan this size usually calls for strong credit, several years in business, solid collateral, and a debt-to-equity ratio that signals repayment capacity. Most banks won't touch it without audited financials.
The SBA 7(a) program allows loans up to $5 million, making it the most realistic path for working capital loans for small businesses at this size. Nanotom Capital is a business funding broker; we're not the lender. We help you compare your options, and we can connect you with a partner that handles SBA loans.
Realistically, if you need $1 million in working capital for small business operations, you're in bank or SBA territory. Build your credit file and financial history accordingly.
Pros and Cons of Working Capital Loans
A working capital loan for small business solves a specific problem. It's not a fit for every situation. Know what you're getting into before you apply.
Pros | Cons |
|---|---|
Fast access to cash; online lenders fund in 24–72 hours | Higher rates than traditional term loans, especially online |
No equity dilution; you keep full ownership | Short repayment terms can strain monthly cash flow |
Flexible use of funds; payroll, inventory, rent, anything operational | MCAs require daily or weekly repayment from revenue |
Bridges seasonal revenue gaps without disrupting operations | Most lenders require a personal guarantee |
Short approval timelines for businesses that qualify online | Doesn't fix structural cash flow problems; just delays them |
That last con is the one most owners ignore. A working capital small business loan buys time, full stop. If your margins are thin, your receivables are slow, and your expenses are growing faster than revenue, borrowing doesn't fix that. It adds a repayment obligation on top of an already stressed operation.
If your business has consistent revenue but a temporary gap, a small business working capital loan is often a smart move. If cash flow deficits are chronic, address the root cause first with better working capital management strategies before taking on more debt.
Are Working Capital Loans a Good Idea?
The honest answer is: it depends on one thing. Working capital loans for small businesses are a good idea when the cost of borrowing is less than the cost of inaction. That's the only framework that matters.
When a Working Capital Loan Makes Sense
Yes, borrow when:
Your restaurant needs $30,000 for holiday inventory, and you'll turn it 3x in 6 weeks
You're a contractor waiting 60 days on a $200,000 invoice and need bridge funding now
A retailer needs to hire seasonal staff 8 weeks before peak revenue hits
A one-time unexpected expense threatens payroll but next month's revenue covers repayment
You've landed a large contract but lack the cash to fulfill it
In each case, the working capital loan for small business generates a return that exceeds its cost. That's the test.
When to Consider Alternatives Instead
No, skip the loan when:
You're borrowing to cover ongoing operating losses with no revenue growth trend
The cost of capital exceeds your expected margin on the funded activity
You're refinancing existing debt without fixing what created the debt
Cash flow deficits happen every month, not seasonally
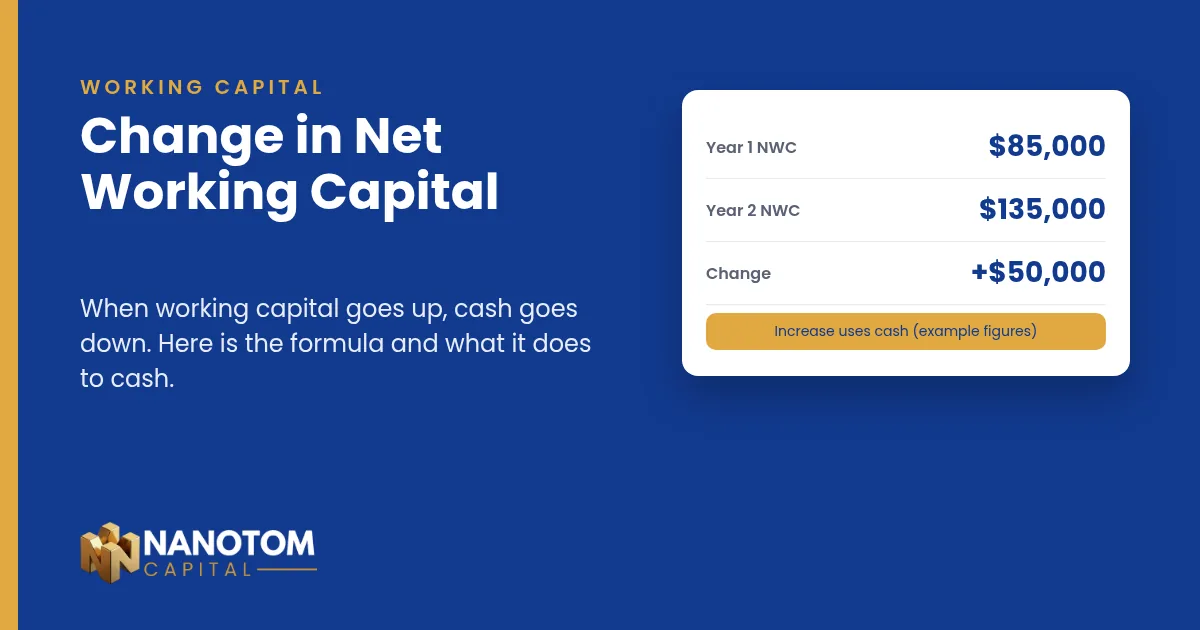
Track your net working capital and changes in your net working capital monthly. If both are trending negative consistently, a small business working capital loan won't fix that; it'll accelerate the problem.
Direct answer: Working capital loans are a good idea for businesses with predictable revenue, a temporary cash gap, and a clear repayment source. They're a poor idea for businesses using debt to mask structural losses.
Revolving vs. Non-Revolving Working Capital Financing
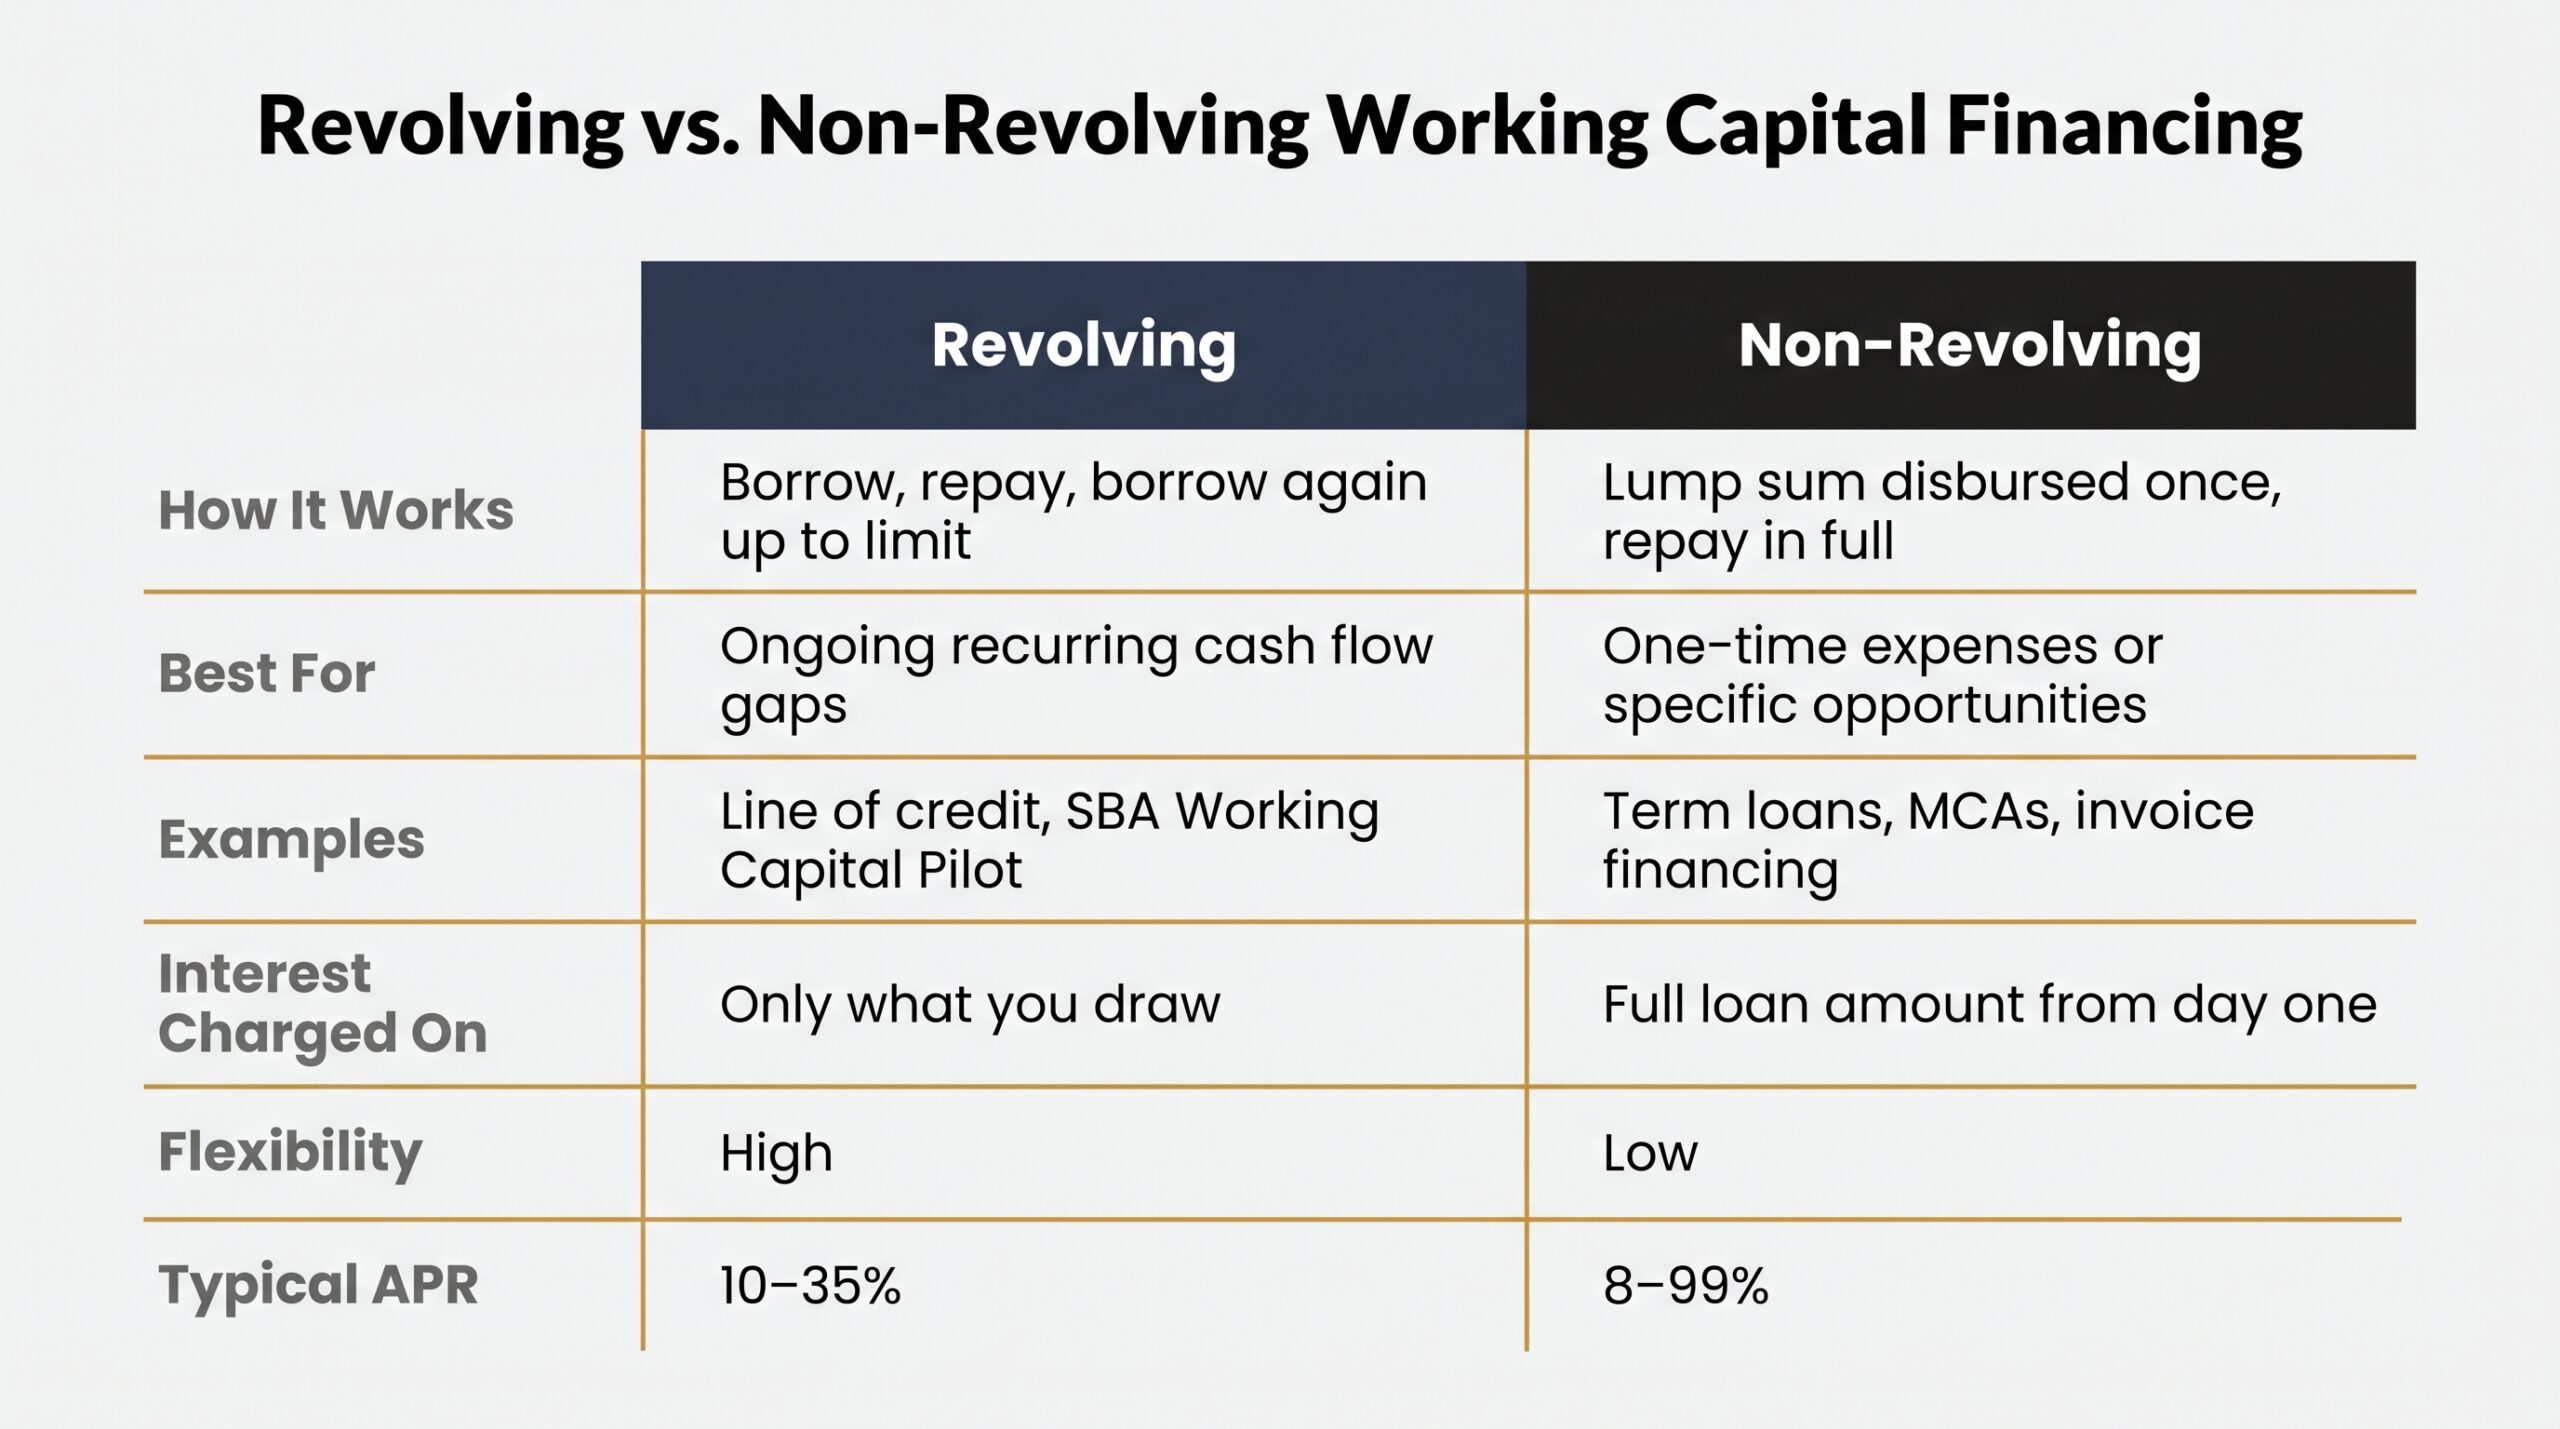
Here's what most guides skip: the structure of your loan matters as much as the rate. Choosing the wrong one creates repayment problems even when you borrow exactly the right amount.
Feature | Revolving | Non-Revolving |
|---|---|---|
How it works | Borrow, repay, borrow again up to your limit | Lump sum disbursed once, repay in full |
Best for | Ongoing, recurring cash flow gaps | One-time expenses or specific opportunities |
Examples | Business line of credit, SBA Working Capital Pilot | Term loans, MCAs, invoice financing |
Cost based on | Only what you draw | Full loan amount from day one |
Flexibility | High; use funds as needed | Low; funds are fixed at closing |
Typical APR range | 10–35% | 8–99% depending on type |
A revolving line of credit is the better small business working capital loan structure if your cash gaps are seasonal or unpredictable. You only pay interest on what you use; a $100,000 line where you draw $20,000 costs you interest on $20,000, not the full amount.
Non-revolving works best when you have a defined, one-time need. Funding a single large inventory purchase or bridging one specific invoice? A term loan or invoice financing gets you there with a clear payoff date.
Refer back to the lender comparison table above to match your structure preference to the right working capital loan lenders before you apply.
Industry-Specific Working Capital Considerations
Cash flow timing problems look different depending on your industry. A working capital loan for small business solves different problems for a retailer than it does for a contractor. Here's what matters by sector.
Retail and E-Commerce: Inventory buildup before Q4 is the classic working capital crunch. You're spending in September and October to capture November and December revenue. A revolving line or PayPal Working Capital works well for e-commerce sellers who need flexible, sales-tied repayment structures.
Restaurants: Food cost cycles and staffing fluctuations hit simultaneously. A catering contract or seasonal menu expansion requires upfront cash 4–6 weeks before revenue lands. Short-term working capital loans for small businesses in this space typically run 6–18 month terms.
Construction: Material costs are paid upfront. Client payments arrive 30–90 days later. That gap is brutal on cash flow. Working capital can bridge the gap between project milestones, and we help you compare your options.
Healthcare: Insurance reimbursement lags of 30–60 days create consistent gaps between service delivery and payment. Equipment financing often overlaps with operational shortfalls, making a small business working capital loan a near-constant need for growing practices.
Professional Services: Project-based billing means income arrives in large, irregular chunks. A working capital loan small business owners in consulting, legal, or marketing use most often is a line of credit. Draw when client payments are delayed, repay when they land.